#TOP1

Navigating the landscape of liability insurance can feel like deciphering a complex legal code. Unlike consumer goods, you aren't buying a physical object. You are purchasing a contractual promise of financial protection against unforeseen legal claims, damages, or injuries. Whether you are a small business owner, a freelance professional, or a property manager, the right liability policy acts as a critical buffer between a single lawsuit and total financial insolvency. Choosing the wrong coverage can leave you exposed to 'silent risks'—gaps in policy language that seem covered until a claim is actually filed.
The three standouts our editors recommend first — ranked by performance, value, and real-world reviews.


| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com Services LLC | 0.00 | No | No | No |


| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com | 9.68 | Yes | Yes | Yes |


| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com | 9.68 | Yes | Yes | Yes |

| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com Services LLC | 0.00 | No | No | No |


| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com | 9.68 | Yes | Yes | Yes |


| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| New Legacy Books | 9.89 | No | No | No |

| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| ThriftBooks-Atlanta | 9.89 | No | No | No |

| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com | 9.68 | Yes | Yes | Yes |

| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| JOHN WILEY AND SONS INC | 0.00 | No | No | No |


| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| Amazon.com | 9.68 | Yes | Yes | Yes |
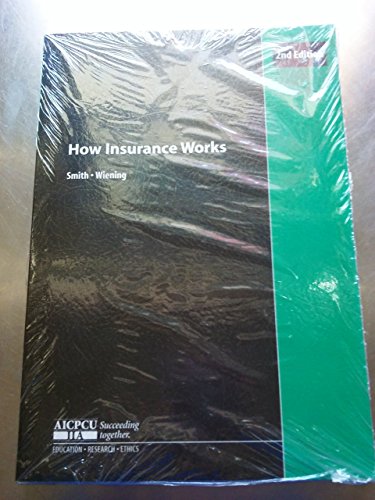

How Insurance Works: An Introduction to Property and Liability Insurance
| SELLER | SELLER SCORE | AMAZON FULFILLED | PRIME | FREE SHIPPING |
|---|---|---|---|---|
| GF Books, Inc. | 9.48 | No | No | No |
Aspiring insurance professionals and finance students require this foundational text to truly grasp the complexities of risk management. This guide from the Insurance Institute of America breaks down the intimidating concepts of property and liability coverage into digestible, logical segments. While this particular copy is a used book, it remains in good condition, making it a much more sensible investment for students on a budget than buying a brand-new edition. It serves as a reliable roadmap through the dense terminology that usually trips up newcomers to the industry. Instead of drowning in legal jargon, you get a clear introduction that builds your confidence from the ground up.

The most common mistake in selecting liability insurance is purchasing a generic policy that doesn't align with your actual daily operations. Liability is not a monolith. It is categorized by the specific type of harm you might cause. For instance, a consultant needs Professional Liability (Errors and Omissions) to protect against mistakes in advice or service delivery. A retail shop owner, however, requires General Liability to cover slip-and-fall accidents or property damage. If you are in construction or healthcare, you may need specialized malpractice or completed operations coverage. Before requesting quotes, perform a 'risk audit' to determine if your primary threat is physical injury, financial loss caused by your errors, or damage to a client's property.
When reviewing policy documents, pay close attention to the 'per occurrence' limit versus the 'aggregate' limit. The per occurrence limit is the maximum the insurer will pay for a single claim, while the aggregate limit is the total amount available for all claims during the policy period. A policy with high limits but a low aggregate might leave you unprotected after your first major legal battle. Additionally, consider the deductible structure. While a higher deductible will lower your monthly or annual premium, you must ensure your business maintains enough liquid cash to cover that deductible immediately should a claim arise. The goal is to find the 'sweet spot' where your premium is manageable but your out-of-pocket exposure is survivable.
The true value of a liability policy is found in what it *doesn't* do. Every policy contains exclusions—specific scenarios where the insurer will refuse to pay. Common exclusions include intentional acts, contractual liabilities, or specific types of cyber-related damages. To bridge these gaps, look for providers that offer 'endorsements' or 'riders.' These are add-ons that expand your coverage to include niche risks, such as product liability for manufacturers or employment practices liability for companies with staff. Never assume a standard policy covers everything. Always ask for a plain-language summary of what is explicitly excluded.
A liability policy is only as good as the company's ability to defend you in court. When selecting a provider, look beyond the premium price and investigate their claims-handling reputation. Do they offer legal defense services as part of the policy? In many liability cases, the cost of hiring an attorney to defend a frivolous lawsuit can exceed the cost of the actual settlement. A provider with a robust legal team and a history of efficient, fair claims processing is worth a premium. Check financial strength ratings from independent agencies to ensure the insurer has the capital reserves to honor large-scale judgments.
Quick answers about Liability Insurance before you buy.
Share of top-ranked products by brand, from our editorial analysis.
We've carried out a comprehensive analysis of 100 reviews on Liability Insurance, using our selection criteria to identify the best options in the categories. Our findings reveal that most customers typically select Liability Insurance priced around $56.63, with top brands including and actex pubns inc.
Our team of expert editors reviewed these high-quality items and handpicked the top 11 Liability Insurance for your consideration. We've also done extensive research on numerous sellers, identifying the best ones in the categories category — including amazon.com, amazon.com services llc, thriftbooks-atlanta and new legacy books and discount text books and more.
We are dedicated to assisting our users in finding the right law Products based on their needs, saving them considerable time when choosing which Liability Insurance to buy. We take pride in the number of satisfied users we've helped through our thorough and insightful reviews.
Compare the top 11 picks at a glance — select a column to sort.


